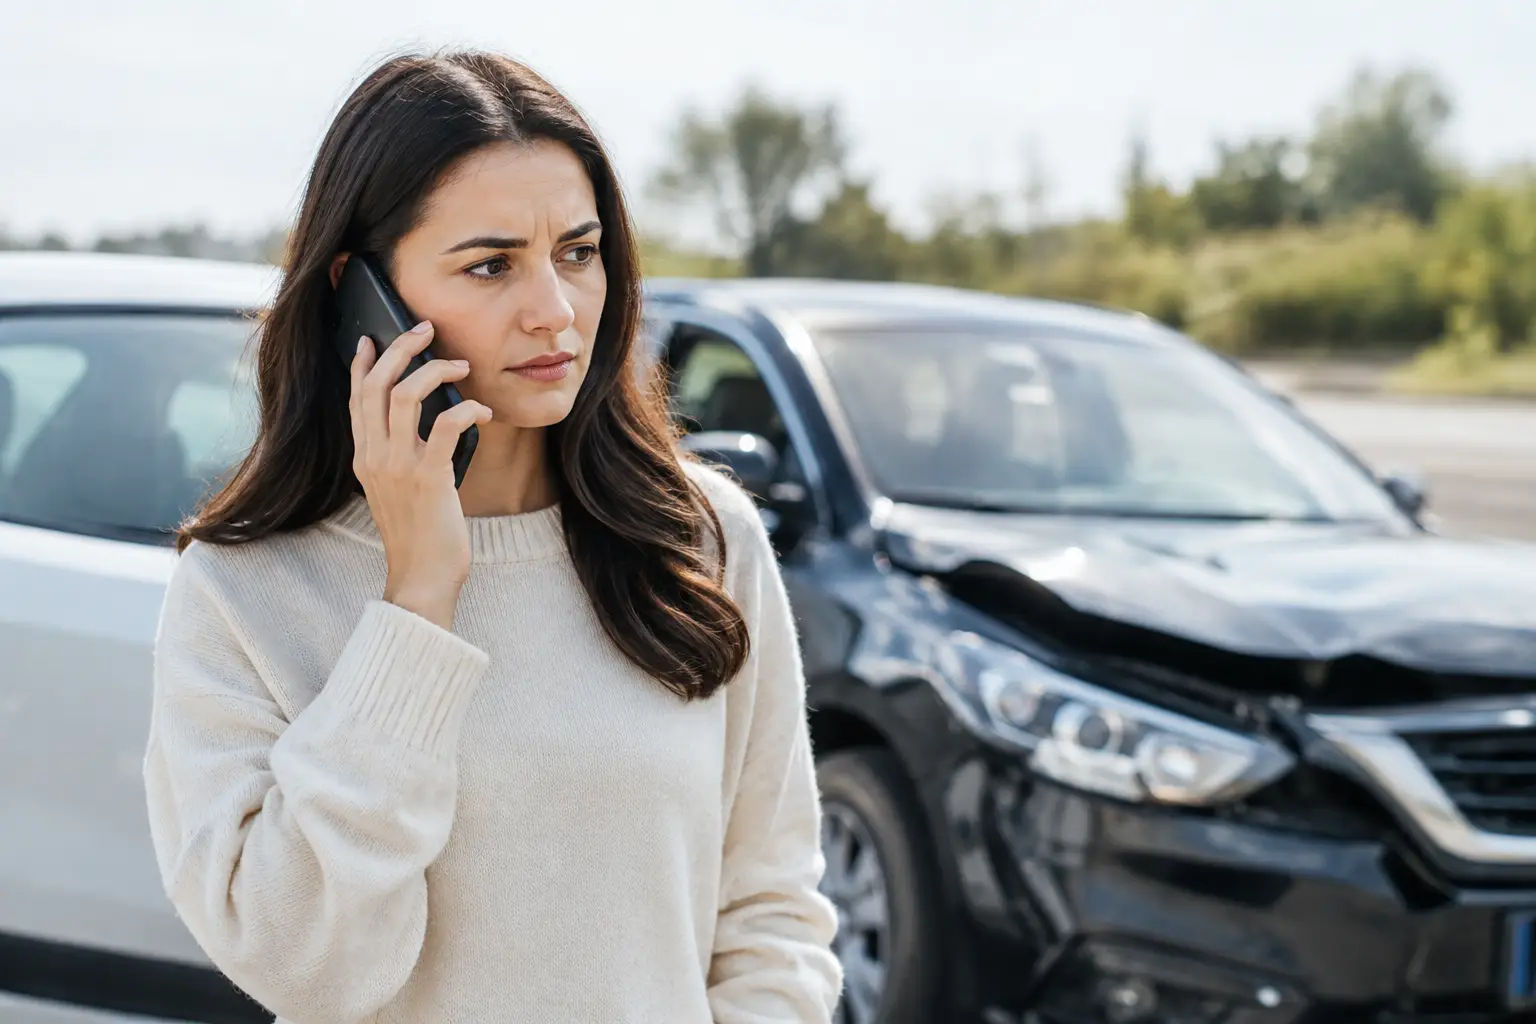
The phone may ring before you have even made it home from the emergency room. Knowing how to handle insurer calls can protect your family from saying something that is later used to reduce or deny a claim. You do not have to argue with an adjuster, prove your case on the spot, or accept a quick offer while you are still trying to understand your injuries.
Insurance companies often move quickly after a crash. Their representatives may sound kind, concerned, and ready to help. Sometimes they are. But their job is also to control the cost of the claim. That creates a conflict when you are hurt, unable to work, worried about medical bills, or grieving someone you love.
How to Handle Insurer Calls Without Hurting Your Claim
Start by finding out who is calling. The other driver’s insurance company and your own insurance company have different roles. You may have duties under your own policy, such as reporting the collision or providing basic information. The other driver’s insurer does not have the same relationship with you, and you are generally not required to give that company a detailed statement right away.
When you answer, keep the conversation short and calm. Ask for the adjuster’s name, insurance company, phone number, claim number, and the name of the person or business they insure. Write down the date and time of the call. You can say that you are receiving medical care, that you are not prepared to discuss the accident in detail, and that you will follow up after you have had an opportunity to review your situation.
A simple response can be enough: “I am still being evaluated and am not ready to give a recorded statement. Please send any questions or documents to me in writing.” You do not need to fill silence, guess at facts, or defend your actions.
Do not guess about injuries or fault
After an accident, people often minimize what happened. They may say, “I’m fine,” because they are trying to be polite or because the full pain has not appeared yet. Neck, back, brain, and internal injuries can take time to become clear. A statement that you felt fine immediately after a collision may later be used to question the seriousness of your condition.
The same is true of fault. Do not speculate about speed, distance, traffic signals, weather, or what another driver may have seen. Even a familiar phrase such as “I never saw them” can be taken out of context. Stick to information you know for certain, such as your name, contact details, the date of the crash, and where it occurred.
If you have already made a statement, do not panic. A single call does not automatically end a claim. It does mean that you should be careful going forward and get guidance before giving further details.
Be cautious with recorded statements
An adjuster may say a recorded statement is routine. It may be routine for the insurer, but that does not mean it is risk-free for you. Questions can be broad, repetitive, or framed in a way that encourages an incomplete answer. You may be asked about past injuries, your medical history, the sequence of events, or activities since the crash before you have all the information needed to respond accurately.
You can politely decline a recorded statement from the other party’s insurer until you understand your rights. Your own carrier may request one as part of its investigation, depending on your policy and the circumstances. Even then, it is reasonable to ask what the statement will cover and to seek legal advice beforehand, particularly after a serious injury, truck crash, workplace incident, or fatal accident.
What Insurers May Ask For and What to Protect
Claims adjusters commonly request photographs, medical authorizations, repair estimates, wage information, and access to records. Some requests are appropriate. Others may be broader than necessary.
For example, an insurer may need documentation related to injuries caused by the crash. A blanket medical authorization, however, may give access to years of unrelated records. Those records can be searched for preexisting conditions or unrelated complaints that the insurer may use to challenge the claim. Prior health conditions do not automatically prevent recovery when a collision worsens an injury, but the facts should be evaluated carefully.
Before signing anything, read it fully. Do not sign a release, authorization, or settlement document just because an adjuster says it will “move things along.” A release can end your right to seek further compensation, including compensation for treatment you may need months later.
Keep copies of every document you send or receive. Save emails, letters, voicemails, medical bills, prescriptions, appointment notices, photographs, and repair records. A notebook or notes app can help you track symptoms, missed work, mileage to medical visits, and calls with insurance representatives. Details that seem small in the first week can matter later.
Watch for a Fast Settlement Offer
A quick settlement offer can feel like relief when bills are arriving and work is on hold. But early offers often come before doctors know the full extent of an injury. Once you accept and sign a release, you may have no path to request more money if surgery, therapy, complications, or lasting limitations follow.
This does not mean every settlement offer is unfair or that every case requires a lawsuit. Some claims can be resolved without lengthy litigation. The question is whether the offer accounts for the actual harm, not just the first emergency-room bill or the visible damage to a vehicle.
Consider the full picture: current and future medical care, time away from work, reduced ability to earn income, pain, physical limitations, property losses, and the impact on daily family life. In a wrongful death claim, surviving family members may also be facing funeral expenses, lost support, and a loss that cannot be reduced to a spreadsheet.
If an adjuster gives you a deadline, ask for the offer in writing. A deadline may be negotiable, and pressure is not a reason to sign away a claim before you are ready.
Keep Your Own Insurer Informed, but Stay Precise
Your own insurer may provide coverage that matters after a crash, including medical payments coverage, uninsured or underinsured motorist coverage, or collision coverage for vehicle repairs. Prompt notice can be important. If you are unsure what coverage you carry, ask for a copy of the policy and a written explanation of available benefits.
Still, accuracy matters in every call. Give truthful, basic information and avoid guessing. If you do not know the answer, say so. If you need to review a document, medical record, or police report first, say that instead of estimating.
Do not let uncertainty about a police report stop you from protecting yourself. Reports can contain errors, and they are only one part of the evidence. Photos, witness accounts, video footage, vehicle data, medical evidence, and a careful investigation may all help establish what happened.
When It Is Time to Let a Lawyer Take the Calls
It is wise to speak with a personal injury lawyer early when injuries are serious, fault is disputed, multiple vehicles are involved, a commercial truck was involved, or an insurer is pushing for a recorded statement or quick settlement. Families should also seek guidance quickly after a fatal crash or another wrongful death incident.
Once you hire a lawyer, the insurance company can communicate through your legal team about the claim. That gives you room to focus on treatment and your family while someone else handles requests, investigates the collision, gathers records, and evaluates the insurance coverage available.
At Downs Law Firm, injured people and grieving families can discuss their situation in a free consultation without upfront legal fees. A case can be prepared for settlement discussions while also being treated seriously enough to go to court when an insurer refuses to deal fairly.
You do not have to have every record, every answer, or a perfectly organized file before asking for help. Save what you can, take care of your health, and give yourself permission to say, “I am not ready to discuss that right now.” Protecting your words in the first days after an accident can protect your family’s recovery in the months ahead.