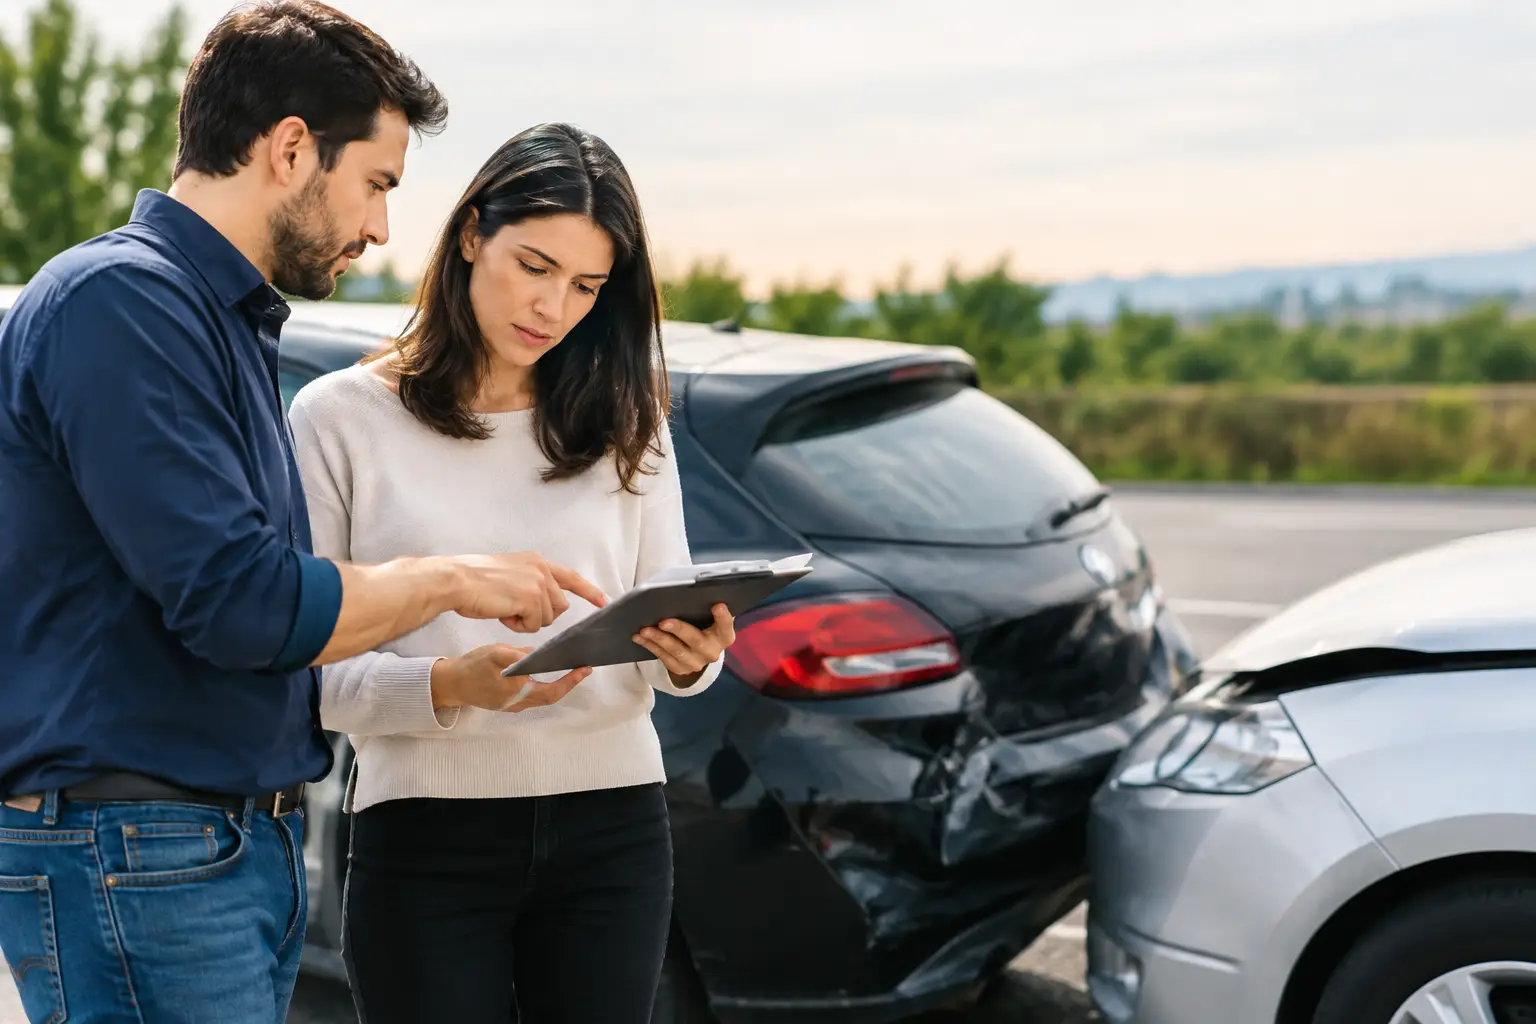
A settlement check can arrive when a family is under real pressure. Medical bills are coming in, a paycheck may have stopped, the vehicle may be gone, and the insurance adjuster sounds helpful on the phone. That is exactly why accident victims should pause before they accept an offer. To avoid early settlements, you need enough information to understand what the crash has truly cost and what it may continue to cost your family.
An early offer is not necessarily a fair offer. It is often an insurer’s attempt to close a claim before the full picture emerges. Once you sign a release, you generally give up the right to seek more money later, even if your injuries worsen or new medical problems appear.
Why insurers make fast settlement offers
Insurance companies are businesses, and settling a claim quickly can limit what they pay. An adjuster may contact you shortly after a wreck, express concern, and offer money for repairs, medical bills, or a general release. The conversation can feel reassuring when everything else feels uncertain.
But the first days and weeks after a collision are usually the worst time to put a final value on an injury. Adrenaline can hide pain. A strained neck or back may become more painful after several days. A concussion may not be fully recognized until headaches, dizziness, memory trouble, or changes in mood interfere with work and home life. Surgery, physical therapy, follow-up imaging, and time away from work may still be ahead.
This is particularly serious after a commercial truck crash, motorcycle collision, or other high-force impact. The visible damage to a vehicle does not tell the whole story about a brain injury, spinal injury, internal injury, or chronic pain. Families grieving a fatal accident also need time and careful guidance before discussing a final wrongful death settlement.
What an early settlement can leave out
A fair claim should account for more than the emergency-room bill. Depending on the circumstances, compensation may involve past and future medical care, lost income, reduced ability to earn a living, property damage, physical pain, emotional distress, and the effect an injury has on daily life. In a wrongful death claim, surviving family members may face separate losses that require careful evaluation.
An early offer may reflect only the bills the insurer has seen so far. It may not account for a recommended surgery, recurring treatment, future medication, rehabilitation, help needed at home, or income you will lose while recovering. It also may not reflect the disruption of no longer being able to lift a child, work a physically demanding job, sleep comfortably, or take part in the routines that held your family together.
The value of a claim depends on the evidence, available insurance coverage, the severity and permanence of the injury, who was at fault, and the laws that apply. There is no responsible one-size-fits-all number. What matters is whether the offer is grounded in a complete and supported understanding of your losses.
How to avoid early settlements without hurting your claim
You do not have to argue with an adjuster or make a final decision during an unexpected call. It is reasonable to say that you are still receiving medical care and are not prepared to discuss settlement. Be polite, but do not let urgency from the insurer become urgency for your family.
Seek medical attention promptly and follow the treatment plan you are given. Gaps in care can affect your health and may give an insurer an argument that an injury was not serious or was unrelated to the crash. If a treatment is difficult to afford or schedule, document the problem and discuss it with your provider.
Keep records as you go. Save medical paperwork, pharmacy receipts, repair estimates, towing bills, work restrictions, pay stubs, and communications from the insurance company. A simple journal can also help. Write down pain levels, missed workdays, activities you cannot do, and symptoms that affect sleep, concentration, or family life. These details can become harder to remember months later.
Do not give a recorded statement or sign broad medical authorizations just because an adjuster requests them. A statement may be used to minimize your injuries or shift blame, and a broad authorization can give the insurer access to health information that has nothing to do with the wreck. There may be situations where information is appropriate to provide, but you should understand the request before agreeing.
Be careful with social media as well. A photo or short post rarely tells the complete story, yet an insurer may attempt to use it that way. It is wise not to post about the accident, your treatment, or your activities while a claim is pending.
Do not confuse a repair payment with a full injury settlement
Handling property damage can be necessary. You may need a rental vehicle, repairs, or payment for a totaled car. Resolving that portion of the matter does not always require settling your bodily injury claim at the same time.
Read every document before signing. Some paperwork may contain release language that reaches farther than you expect. If a document says it resolves all claims, do not assume it is limited to vehicle damage. Ask questions before you sign away rights you may need later.
Evidence can disappear while you recover
Waiting to accept a settlement does not mean waiting to protect the case. In fact, early investigation can be vital. Crash-scene evidence can change quickly. Camera footage may be erased, vehicles can be repaired or destroyed, witnesses can become difficult to locate, and a trucking company may possess records that need to be preserved.
A thorough investigation may include photographs, police reports, witness statements, vehicle data, cell phone records where appropriate, employment records, and medical documentation. In truck cases, it can also involve driver logs, inspection materials, maintenance records, and information about the company responsible for the vehicle.
This is one reason a quick offer deserves close attention. If fault is disputed, or several people or companies may share responsibility, accepting before the facts are developed can mean accepting far less than the claim warrants. Louisiana, Arkansas, and Mississippi each have legal rules and deadlines that can affect a case, so getting advice early can protect options even if you are not ready to make any final decision.
When it makes sense to speak with a lawyer
Not every minor claim requires a lawsuit or a long dispute. If injuries are fully resolved, fault is clear, and the available information supports the offer, a settlement may be appropriate. The key is making that choice with clear information, not because an adjuster has created pressure.
It is particularly wise to seek legal guidance after a serious injury, an accident involving an 18-wheeler or company vehicle, a crash with disputed fault, a collision involving an uninsured or underinsured driver, or a death. A lawyer can review the offer, identify evidence that should be preserved, communicate with insurers, and explain whether the proposed release is broader than it appears.
At Downs Law Firm, families can discuss their situation without upfront legal fees. The firm is paid only if there is a financial recovery, allowing injured people to get answers without adding another immediate bill to an already difficult time.
You do not need to have every record organized before asking for help. Bring what you have, keep following your medical care, and give yourself room to understand the road ahead. A fast check may relieve pressure for a moment, but protecting your family’s recovery can be worth far more than a rushed decision.